A Transparent, Step-by-Step Mortgage Process
The mortgage process does not have to be confusing. While every transaction is different, most loans follow a similar path. Ink Mortgage Group helps Florida borrowers understand each step, organize the necessary documentation, and stay coordinated with lenders, real estate professionals, and closing agents.
We do not promise guarantees we cannot keep. Instead, we focus on honest communication, thorough file preparation, and helping qualified borrowers find lending options that fit their actual situation.
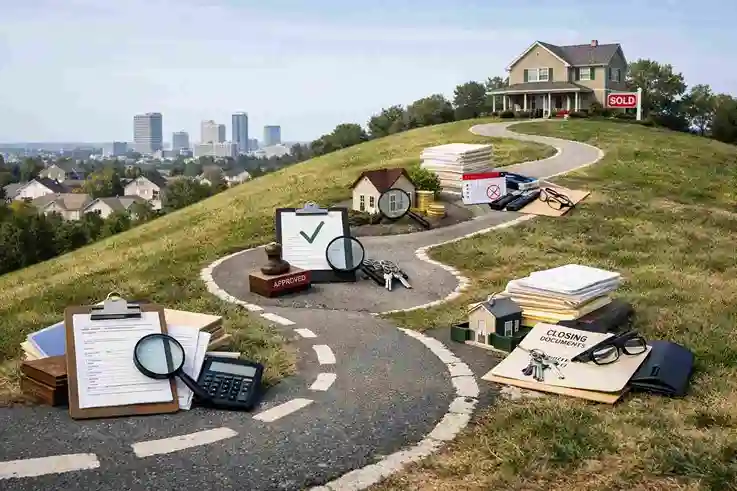
The Four Phases of a Mortgage Transaction
Initial Review & Strategy
What happens here:
The first step is a conversation, not an application. We take time to understand your goals, financial profile, property type, and timeline.
What you can expect from us:
- A realistic assessment of which loan options may be available
- Explanation of documentation you are likely to need
- Clear discussion of potential challenges upfront
- No pressure and no exaggerated promises
Documentation & File Preparation
What happens here:
Once we identify potential loan options, we help you assemble a complete, organized loan file. A well-prepared file moves faster and faces fewer surprises.
What you can expect from us:
- A specific list of documents tailored to your scenario
- Review of documents for completeness before submission
- Identification of any missing items or potential red flags
- Guidance on how to submit documents securely
Lender Submission & Underwriting
What happens here:
We match your file with lending partners appropriate for your scenario. Once you choose a lender and loan program, we submit your file for formal underwriting review.
What you can expect from us:
- Communication of lender questions or conditions
- Coordination of appraisal and other third-party services
- Ongoing updates on file status
- Assistance responding to underwriter requests
Closing & Funding
What happens here:
Once underwriting conditions are satisfied, the lender issues final approval. Closing documents are prepared, and a closing date is scheduled.
What you can expect from us:
- Review of closing documents before you sign
- Coordination with all parties to keep closing on track
- Availability to answer last-minute questions
How Long Does the Mortgage Process Take?
| Loan Type | Typical Timeline |
|---|---|
| Conventional / FHA / VA / USDA | 30–45 days |
| Jumbo Loans | 30–60 days |
| Non-QM / Bank Statement Loans | 30–60 days |
| DSCR Investor Loans | 30–45 days |
| Construction Loans | Varies significantly (45–90+ days depending on builder and draw schedule) |
| Small Commercial Loans | 45–90 days (varies by property and lender) |
Factors That Can Impact Your Timeline
Common delays and how we help address them:
Incomplete documentation
We provide a clear checklist upfront and review your file before submission.
Appraisal issues
We help coordinate appraisal orders and address value or condition concerns.
Condo or HOA review
We identify potential condo approval issues early and help gather required documents.We help coordinate appraisal orders and address value or condition concerns.
Title or lien issues
We work with title companies to resolve any title problems before closing
Borrower credit changes
We advise against opening new credit, making large purchases, or changing jobs during the process.
Self-employment or income complexity
We help organize alternative documentation before submitting to lenders.
Frequently Asked Questions About the Mortgage Process
Do I need a mortgage pre-approval before looking at homes?
Pre-approval is not required by law, but many sellers and real estate agents expect it. We can help you determine whether a full pre-approval or a preliminary loan review makes sense for your situation.
Will applying for a mortgage affect my credit score?
Yes, most lenders will pull a credit report. However, multiple mortgage inquiries within a typical shopping window (often 14–45 days, depending on scoring model) are generally treated as a single inquiry. We can discuss timing before pulling credit.
Can I get a mortgage if I am self-employed?
Yes. Self-employed borrowers may qualify using tax returns, bank statements, or alternative documentation programs, depending on the loan type and lender guidelines.
What is the difference between pre-qualification and pre-approval?
Pre-qualification is typically an informal estimate. Pre-approval involves documentation review and credit check and carries more weight with sellers and real estate agents.
Do you charge a fee for your services?
Ink Mortgage Group is compensated by lenders in most transactions, not directly by borrowers. We will disclose all fees and compensation clearly before you commit to any loan program.
Ready to Start the Conversation?
You do not need perfect credit, simple income, or a standard loan file to begin. You just need a clear understanding of your options and a practical next step.
Let's review your mortgage options
Buying, refinancing, investing, purchasing commercial property, or working through a complex scenario, we'll help you evaluate your options and decide the next practical step.
- Address608 SW Bayshore Blvd, Port St. Lucie, FL 34983
- Email[email protected]
- Open hoursMonday – Friday, 8:00 AM – 5:00 PM